How Workforce Mix Affects Payroll Tax Savings Potential — What Every Employer Should Model
Learn how your workforce mix W-2 headcount, participation rates, and employment type directly affects your Section 125 FICA payroll tax savings potential.
When employers model their potential FICA payroll tax savings from a Section 125 / SIMERP strategy, the first number they reach for is total W-2 headcount. That is the right starting point, but it is not the complete picture.
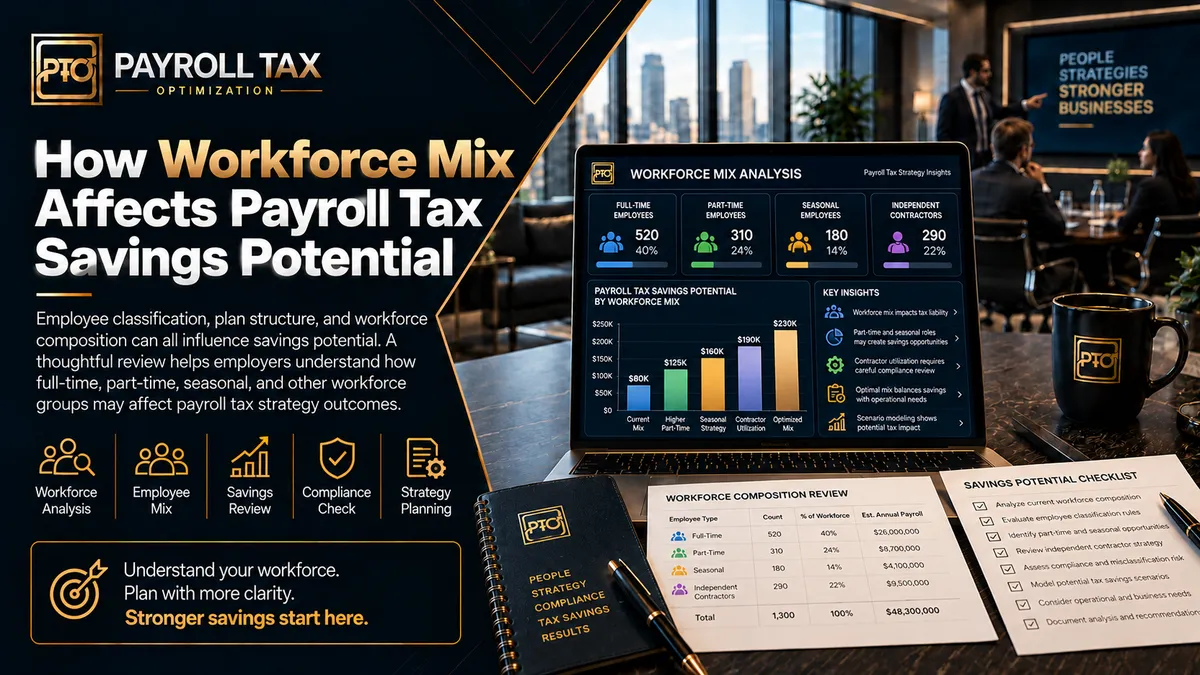
The actual savings an employer captures depend not just on how many W-2 employees they have, but on how that workforce is composed: the ratio of salaried to hourly employees, the split between full-time and part-time workers, the proportion of the workforce that has qualifying health coverage, and the participation rate the employer can realistically expect from each employee category. Understanding how workforce mix affects payroll tax savings potential is what separates an accurate savings model from an overstated one, and it is what allows CFOs and HR directors to build a financial projection they can present with confidence rather than disclaim as a vendor estimate.
For employers whose workforce composition is well-aligned with the program’s design large hourly populations, stable W-2 employment, existing qualifying coverage, and strong participation potential the Section 125 / SIMERP structure may generate $640–$1,120 per qualifying W-2 employee annually in employer FICA savings. For employers whose workforce composition introduces variables that moderate the baseline, understanding those variables produces a realistic projection rather than a disappointing implementation outcome. The employer payroll tax savings overview provides the full program context, and this blog focuses specifically on how workforce composition shapes the savings calculation.
The Problem: Single-Input Savings Models Produce Overconfident or Underconfident Projections
The most common savings modeling error employers make is treating total W-2 headcount as the only variable. Multiply headcount by $640 or $1,120, divide by 12, and the result looks clean and straightforward. It is also systematically inaccurate in either direction for most real employer workforces.
An employer who models $640 per employee against 400 W-2 employees and projects $256,000 in annual savings without accounting for participation rate, coverage eligibility, or part-time headcount may be building a projection that overstates what the program will actually deliver, creating an implementation outcome that underwhelms relative to expectation.
An employer who looks at 400 total workers, 280 W-2 employees, and 120 contractors and models zero savings because they treated total headcount rather than qualifying W-2 headcount as the input has understated the opportunity significantly on the W-2 side.
Both errors come from the same source: an incomplete understanding of which workforce variables affect the savings calculation and how. Correcting for those variables produces a projection that holds up — one that CFOs can model confidently and HR directors can use to set realistic expectations before enrollment begins.
The full Section 125 compliance framework is available for employers who want to validate the legal foundation of the per-employee savings figure before applying workforce mix variables to their own model.
Missed Opportunity: Inaccurate Modeling That Leads to No Decision at All
One of the most consequential effects of inaccurate workforce mix modeling is not an overstatement or an understatement of savings; it is a stall. Employers who cannot build a savings projection they trust internally tend not to bring the evaluation to a conclusion. The open question about whether the numbers are real keeps the decision from being made, and every cycle that passes without a decision is a cycle where FICA savings are not captured.
Here is what qualifying employers at various workforce sizes may be leaving uncaptured each year while a modeling question remains unresolved:
100 qualifying W-2 employees — Potential annual FICA savings: $64,000–$112,000 | Monthly: $5,333–$9,333
200 qualifying W-2 employees — Potential annual FICA savings: $128,000–$224,000 | Monthly: $10,667–$18,667
300 qualifying W-2 employees — Potential annual FICA savings: $192,000–$336,000 | Monthly: $16,000–$28,000
500 qualifying W-2 employees — Potential annual FICA savings: $320,000–$560,000 | Monthly: $26,667–$46,667
1,000 qualifying W-2 employees — Potential annual FICA savings: $640,000–$1,120,000 | Monthly: $53,333–$93,333
Actual savings depend on W-2 workforce composition, payroll structure, and employee participation rates.
These figures represent the range available to qualifying employers, and a properly built workforce mix model places the employer’s realistic savings within that range rather than at an arbitrary point within it. The employer FAQ library on Section 125 and SIMERP covers the savings formula mechanics in detail, including how per-employee figures are derived and what participation rate assumptions apply across different workforce types.
Workforce Variable #1 — Total Qualifying W-2 Headcount
The foundation of every savings model is total qualifying W-2 headcount, and this number requires more precision than most initial estimates provide.
What counts toward qualifying headcount:
All W-2 employees who meet the plan’s eligibility criteria, typically defined by minimum hours thresholds, employment status, and qualifying health coverage, contribute to the qualifying headcount. This includes:
Full-time salaried employees
Full-time hourly employees
Eligible part-time W-2 employees who meet minimum hours requirements and have qualifying coverage
Employees across all locations and entities when the employer operates multiple sites
What does not count:
Independent contractors, 1099 workers, and self-employed individuals are outside the qualifying headcount; the §3121(a)(5)(G) FICA exclusion applies only to W-2 employment relationships where the employer bears the FICA obligation.
Modeling implication:
Employers who exclude eligible part-time and hourly W-2 employees from their initial headcount estimate consistently understate the qualifying headcount and understate the savings accordingly. For labor-intensive employers in manufacturing, healthcare, and retail where hourly and part-time W-2 populations are significant, including these employees in the qualifying count can materially change the savings projection.
Workforce Variable #2 — Employee Participation Rate
Participation rate is the variable that most directly determines where within the per-employee savings range the employer’s actual outcome will fall, and it is the variable most frequently omitted from initial savings presentations.
What drives participation rates:
Participation in the Section 125 election is voluntary. The rate at which eligible employees elect to participate depends on several factors:
How clearly the take-home pay benefit is communicated. Employees who understand that the election may increase their take-home pay by approximately $150 per pay period are significantly more likely to enroll than employees who receive a generic benefits notice with no paycheck context.
Workforce composition by employment type. Hourly employees for whom $150 per pay period represents a meaningful percentage of take-home compensation tend to show strong participation when the benefit is communicated clearly. Highly compensated salaried employees may show more variable participation depending on their existing benefit election mix.
Employer communication infrastructure. Organizations with strong HR communication channels, manager-level benefit awareness, and clear enrollment materials tend to achieve higher participation than those relying on self-service enrollment without active support.
Realistic participation rate ranges:
Conservative base case: 50–60% of qualifying W-2 employees
Realistic base case: 65–75% of qualifying W-2 employees
Optimistic case: 80–85% of qualifying W-2 employees where workforce composition and communication quality support it
Modeling implication:
An employer with 300 qualifying W-2 employees who models at 70% participation 210 effectively participating employees at $53.33 per month produces a realistic monthly savings figure of approximately $11,200 and an annual savings figure of approximately $134,400. The same employer modeling at 100% participation produces $192,000 annually, a figure that looks compelling but will not reflect the actual program outcome. Building the savings model at 65–75% participation as a base case produces a number that implementation results can meet or exceed, rather than one the program starts behind.
Workforce Variable #3 — Full-Time vs. Part-Time Composition
The ratio of full-time to part-time W-2 employees affects the qualifying headcount, the participation rate, and the per-employee savings figure in ways that compound across the workforce.
How full-time employees affect the model:
Full-time W-2 employees, both salaried and hourly, are typically the most straightforward qualifying population. They are consistently on payroll throughout the plan year, their FICA exposure is predictable cycle to cycle, and their participation decisions tend to be stable once made at enrollment.
How part-time employees affect the model:
Eligible part-time W-2 employees who meet the plan’s minimum hours requirements and have qualifying health coverage contribute to the qualifying headcount and to the FICA savings. However, their per-cycle FICA exposure is lower than that of full-time employees because their taxable wages per cycle are lower. The $53.33 per participating employee per month figure reflects the savings across a workforce with a normal distribution of wage levels. In workforces with a high proportion of low-wage or minimal-hours part-time employees, the per-employee savings may fall toward the lower end of the $640 annual range rather than the midpoint or upper end.
Modeling implication:
Employers whose qualifying headcount includes a significant part-time W-2 population should model the lower end of the per-employee savings range as the base case and verify with the TPA that the plan document’s eligibility criteria correctly reflect the hours and coverage thresholds intended for the part-time population.
Workforce Variable #4 — Health Coverage Enrollment Rate
The ACA compliance design of the SIMERP requires that participating employees have qualifying major medical coverage in place. This means the program’s participation pool is effectively limited to employees who are enrolled in or eligible for and enrolled in ACA-compliant health coverage.
How coverage enrollment rate affects the model:
In most employer populations, a significant majority of W-2 employees who are offered coverage elect to enroll. But for employers where a meaningful percentage of employees waive coverage either because they are covered under a spouse’s plan, are enrolled in government programs that may not qualify, or have opted out for other reasons — the effectively participating headcount is further reduced below the total qualifying W-2 count.
Modeling implication:
Employers who know their coverage enrollment rate, typically available from the benefits administration data, can incorporate it as a multiplier in the savings model. A qualifying W-2 headcount of 300 employees where 85% are enrolled in qualifying coverage produces an effectively eligible population of 255, and applying a 70% participation rate to that population produces approximately 178 effectively participating employees.
Workforce Variable #5 — Workforce Stability and Turnover Rate
The Section 125 election is tied to the plan year. Employees who leave during the plan year and are replaced by new employees require new enrollment processing. During the transition period between departure and new-hire enrollment, the outgoing employee’s election contribution to the FICA savings is interrupted.
How turnover affects the model:
For employers with very high turnover rates in retail, hospitality, and seasonal operations, the effective participating headcount at any given payroll cycle may be meaningfully lower than the enrolled headcount because a portion of enrolled employees has left and their replacements have not yet completed enrollment.
For employers with low to moderate turnover, the program’s strongest-fit industries, including manufacturing, automotive, school districts, and healthcare, this variable has minimal impact on realized savings relative to the model.
Modeling implication:
Employers in high-turnover environments should apply a turnover adjustment to their participation rate assumption, effectively treating the realistic average participating headcount across all payroll cycles as the modeling base rather than the peak enrollment headcount. A 20% annual turnover rate does not reduce the savings by 20%; the timing of departures and new enrollments means the realized impact is typically smaller, but it should be acknowledged in any model presented to CFO-level leadership.
Industry-specific workforce composition guidance, including how turnover patterns affect the savings model across automotive dealer groups, manufacturers, school districts, and healthcare networks, is available in how Section 125 applies across industries.
Building the Complete Workforce Mix Model: A Practical Framework
Incorporating all five workforce variables produces a realistic savings model that CFOs can present with confidence. Here is how the complete model works:
Step 1: Start with total W-2 headcount across all locations and entities.
Step 2: Remove non-qualifying W-2 employees, those below the plan’s minimum hours threshold or without qualifying health coverage.
Step 3: Apply a realistic participation rate assumption of 65–75% as a base case to produce effective participating headcount.
Step 4: Apply a turnover adjustment if applicable, typically relevant for employers with annual turnover above 25%.
Step 5: Apply $53.33 per effectively participating employee per month to produce a monthly FICA savings estimate.
Step 6: Multiply by 12 for annual savings. Multiply by 5 for the five-year cumulative view that tends to reframe the evaluation as a strategic decision rather than an administrative one.
Step 7: Run sensitivity analysis at 50%, 65%, and 80% participation to give leadership a range: conservative, base-case, and optimistic, rather than a single point estimate.
This seven-step model produces a savings projection that reflects the employer’s actual workforce composition, not a generic headcount-times-per-employee-figure calculation that ignores the variables that determine where within the savings range the employer will actually land.
Common Workforce Mix Modeling Mistakes Employers Make
Using total workers instead of qualifying W-2 headcount. Total workforce figures that include contractors, part-time employees below minimum hours, or employees without qualifying coverage overstate the qualifying population and the savings that population will generate.
Modeling at 100% participation. No benefit election achieves 100% voluntary participation. Building a savings model at full participation produces a figure that will be missed at implementation, and missed savings projections damage internal confidence in the program more than a conservative estimate that is exceeded.
Ignoring part-time and hourly W-2 employees in the qualifying headcount. These employees are often the largest population in labor-intensive employers, and excluding them understates the qualifying headcount significantly.
Not running sensitivity analysis. A single point estimate presented without a participation rate range gives leadership no way to evaluate downside scenarios. A 50% / 65% / 80% sensitivity range provides the context for a confident internal decision.
Treating the savings model as the vendor’s responsibility. The employer should build an independent savings model using their own verified headcount and realistic participation assumptions and compare it against the vendor’s projection rather than simply accepting the vendor’s figure as the basis for internal decision-making. Additional modeling resources are available through the Section 125 employer guides and resources.
Conclusion
Workforce mix is not a complication in a payroll tax savings model, it is the refinement that makes the model trustworthy. Total W-2 headcount, participation rate, full-time to part-time composition, coverage enrollment rate, and workforce stability each affect where within the $640–$1,120 per employee annual range the employer’s actual savings will land, and how consistently those savings will be generated across every payroll cycle throughout the plan year.
Employers who incorporate all five variables into their savings model arrive at a projection they can present internally with confidence, set enrollment expectations against accurately, and measure implementation results against fairly. That model takes a few additional inputs beyond total headcount, but it produces a financial projection that drives decisions rather than one that invites skepticism.
The starting point is still total qualifying W-2 headcount. The next step is applying the workforce mix variables that make the number accurate.
Ready to Model Your Savings With Workforce Mix Built In?
Get your free savings estimate today. Use the live calculator at Payroll Tax Optimization to model your potential annual and monthly FICA reduction based on your qualifying W-2 headcount, then request your free savings report for a full workforce composition analysis, participation rate assumptions, compliance framework, and implementation timeline. No upfront cost, no obligation, and no need to change your current health plan.